

A prepaid funeral plan lets you choose and pay for your funeral arrangements in advance, so the cost and the decisions are settled before your family ever needs them. Most prepaid funeral plans are either a contract with a funeral home, with your payments held in a state-regulated trust, or a small insurance policy that pays the funeral home when you die. This guide explains how prepaid funeral plans work, what they cost, what is and is not guaranteed, the risks to check before you sign, and the alternatives if you would rather plan ahead without paying ahead.
What Is A Prepaid Funeral Plan?
A prepaid funeral plan, also called a preneed funeral contract, is an agreement in which you select the goods and services you want for your own funeral and pay for them now, either in a lump sum or in installments. The plan records your wishes (burial or cremation, type of service, casket or urn, viewing, flowers, transport) and locks in the provider who will carry them out. When you die, your family contacts the funeral home named in the contract and the plan is put into action.
Prepaying is different from pre-planning. You can pre-plan a funeral, meaning document your wishes and share them with your family, without handing over any money. Prepaying adds the financial step of funding those wishes in advance. Many families do the first without the second, and this article covers both routes.
How Do Prepaid Funeral Plans Work?
Most prepaid funeral plans follow the same three steps.
1. You choose the funeral home and the services. Under the Federal Trade Commission's Funeral Rule, every funeral home must give you an itemized General Price List when you ask about arrangements in person, and it must let you buy only the items you want rather than a package. Use that list to build your plan line by line, and compare it against at least one other provider before committing. Titan Concierge offers free funeral planning help if you would like someone to compare local price lists for you.
2. You sign a preneed contract and choose how it is funded. The contract states exactly what is covered, which prices are guaranteed, how the money will be held, and what happens if you cancel, move, or the funeral home closes. The funding method is either a trust or an insurance policy, explained below.
3. Your family activates the plan at the time of need. They contact the funeral home, present the contract, and the funeral home draws the funds from the trust or files the insurance claim. Any items that were not guaranteed are billed at the current price, and any surplus in the fund is handled according to the contract terms and your state's rules.
Atlas XL (Made in USA)
Sale price
From $1,999
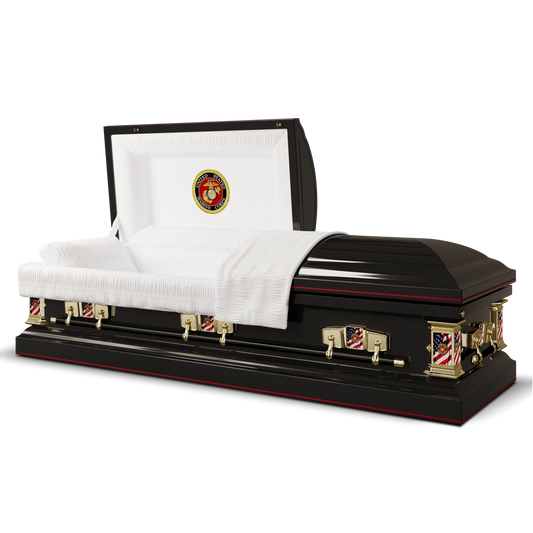
Veteran Premier (Made in USA)
Sale price
$2,299
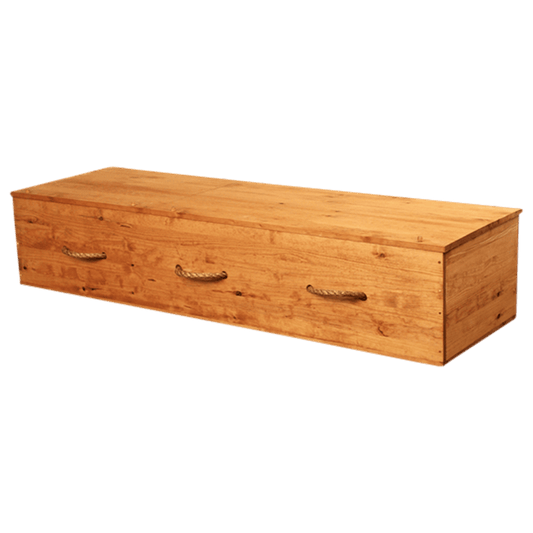
Eco II Pine Box (Made in USA)
Sale price
$1,199


Types Of Prepaid Funeral Plans
Prepaid funeral plans are funded in one of two main ways, and several other arrangements are often grouped with them.
Trust-funded preneed contracts
You pay the funeral home directly, and the funeral home is required by state law to deposit some or all of that money into a trust account managed by a bank or trust company. The required percentage varies by state; some states require 100 percent of your payment to be placed in trust, while others allow the funeral home to keep a portion as a fee. The trust earns interest over time, which is meant to cover price increases between now and the funeral. Revocable trusts can be cancelled and refunded, usually minus an administrative fee. Irrevocable trusts cannot be cancelled by you, which is why they are often used when someone needs to spend down assets to qualify for Medicaid.
Insurance-funded preneed plans
Instead of a trust, your payments buy a small whole-life insurance policy, and the funeral home is named as the beneficiary or assignee. When you die, the policy pays the funeral home directly. These plans are portable in principle, because the policy belongs to you, but they usually require a health questionnaire, and a policy cancelled early may return only its cash value rather than everything you paid. If you are considering this route, read our guide to pre-planning your funeral with a life insurance policy.
Burial insurance and final expense policies
Burial insurance, sometimes sold as final expense insurance, is a life insurance policy with a modest death benefit, typically $5,000 to $25,000, paid to a family member you name. It is not tied to a particular funeral home, so your family can spend it wherever they choose, but it also does not lock in any prices. It is a way of setting money aside for burial or cremation expenses, not a funeral plan in itself.
Payable-on-death bank accounts
A payable-on-death (POD) savings account, sometimes called a Totten trust, is a regular bank account with a named beneficiary who receives the balance immediately on your death, outside of probate. It offers no price guarantee and no contract with a funeral home, but the money stays entirely under your control and can be used at any provider. Many people who want to plan ahead without prepaying pair a POD account with a written plan.
What A Prepaid Funeral Plan Covers
A typical preneed contract can include the funeral home's basic services fee, transfer of the body to the funeral home, embalming or refrigeration, use of the facilities and staff for a viewing and ceremony, the hearse and service vehicles, the casket or coffin, an urn and cremation fee if you choose cremation, an outer burial container or grave liner, and printed materials. Cemetery costs, such as the plot, opening and closing of the grave, and the headstone, are usually purchased separately from the cemetery and are often not part of a funeral home's prepaid plan, so ask about them specifically.
Guaranteed vs non-guaranteed items
The most important line in any prepaid funeral contract is which items are guaranteed. A guaranteed item is locked at today's price; whatever it costs when you die, your family pays nothing more for it. A non-guaranteed item is only estimated, and your family will pay the difference if the price has risen. Funeral homes commonly guarantee their own goods and services but not third-party charges such as the cemetery, clergy honoraria, death certificates, obituary notices, or flowers, because they do not control those prices. Ask for the guaranteed and non-guaranteed items to be listed separately in writing.
How Much Do Prepaid Funeral Plans Cost?
A prepaid funeral plan costs roughly what the same funeral would cost today, plus any administrative or finance charges if you pay in installments. According to the National Funeral Directors Association's most recent member survey, the median cost of a funeral with viewing and burial in the United States is about $8,300, and the median cost of a funeral with viewing and cremation is about $6,280. Neither figure includes the cemetery plot, monument, or flowers. A direct cremation with no service can be arranged for well under $2,000 in most markets, while an elaborate funeral with a premium casket, vault, and cemetery costs can exceed $15,000.
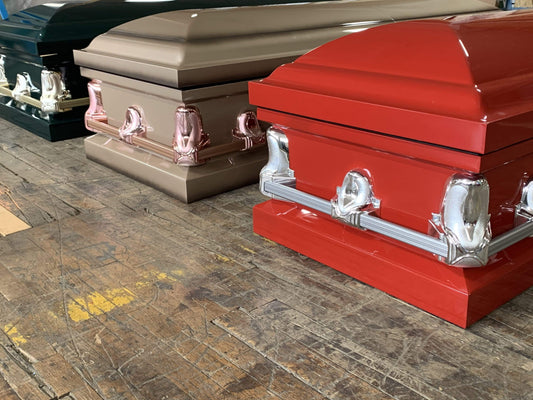
The casket is usually the single largest line item, and it is one you do not have to buy from the funeral home. The Funeral Rule requires funeral homes to accept a casket you purchased elsewhere without charging a handling fee. Buying a casket online typically saves families thousands of dollars compared with funeral home showroom prices, and you can pre-plan a casket with Titan Casket so the choice and the price are settled in advance. For a full breakdown of funeral costs and ways to reduce them, see our guide to paying for a funeral.
Pros And Cons Of Prepaid Funeral Plans
Advantages
Prepaying removes both the financial and the decision-making burden from your family at the worst possible time. Guaranteed items protect against funeral price inflation, which has run ahead of general inflation for decades. Your wishes are recorded with the provider who will carry them out, so there is less room for disagreement among relatives. And an irrevocable preneed contract is generally treated as an exempt asset when applying for Medicaid, within limits set by each state, which is why elder-law attorneys often recommend one during long-term care planning.
Risks and disadvantages
The money is tied up, sometimes for decades, and cancelling a revocable plan usually costs an administrative fee while an irrevocable plan cannot be cancelled at all. If the funeral home closes, changes ownership, or is bought by a chain, the new owner may not honor the original prices unless the contract says so. If you move or die in another state, the plan may not transfer to a funeral home there, or may transfer with a penalty. State trusting requirements vary, and in states that allow the funeral home to keep a portion of your payment, less of your money is protected. Insurance-funded plans can return less than you paid if cancelled early, and some limit the payout in the first years of the policy. Finally, the interest or growth on the fund often goes to the funeral home rather than to your estate, even if the funeral ends up costing less than the fund is worth.
Let Titan Concierge help you plan with clarity, care, and confidence.
Questions To Ask Before You Sign A Prepaid Funeral Contract
The FTC recommends getting clear written answers to these questions before paying for a funeral in advance. What exactly am I paying for, and which items are guaranteed at today's price? Where will my money be held, and what percentage goes into trust or into the policy? What happens to the interest or growth on the fund? Can I cancel, and what will I get back if I do? Can I transfer the plan to another funeral home if I move, and is there a fee? What happens if the funeral home goes out of business or is sold? Will my family be notified about non-guaranteed items and their current prices before the funeral? Where is the contract kept, and who else has a copy?
Keep a copy of the signed contract with your other estate documents and make sure the executor of your will and at least one family member know where it is. A prepaid plan that nobody can find at the time of need is worth nothing. Our end-of-life checklist covers where to keep these records.
Alternatives To Prepaying For A Funeral
You do not have to prepay to plan ahead. The simplest alternative is to write down your wishes using a funeral pre-planning checklist, share it with your family, and set money aside in a payable-on-death account they can access immediately. This keeps your funds liquid and your family free to choose any provider, at the cost of giving up price guarantees.
A middle path is to prepay only the items you control and that carry the largest markup, such as the casket, while leaving the funeral home services to be arranged at the time of need. Because the Funeral Rule prevents funeral homes from refusing or surcharging a casket bought elsewhere, this locks in the biggest saving without tying your family to one provider.
If the reason you are considering a prepaid plan is that you do not want your family to face the process alone, a funeral concierge can fill that gap. Titan Concierge provides funeral planning services that document your wishes in advance and then guide your family through comparing funeral homes, understanding price lists, and handling paperwork when the time comes, without requiring you to prepay a funeral home. It works alongside any of the funding methods above.
Prepaid Funeral Plan FAQs
Is a prepaid funeral plan a good idea?
A prepaid funeral plan is a good idea if you want guaranteed prices, you are confident you will stay in the same area, and you have chosen a stable, well-established funeral home. It is less suitable if you may move, if you want your family to have flexibility, or if you could earn more by keeping the money invested yourself.
What happens to a prepaid funeral plan if the funeral home closes?
If the plan is trust-funded, the money in the trust still belongs to the contract and should be available to another funeral home, though the price guarantees may not carry over. If the plan is insurance-funded, the policy remains in force and can be assigned to a different funeral home. Check your state's funeral board for its specific consumer protections.
Can you get your money back from a prepaid funeral plan?
Revocable trust-funded plans can usually be cancelled for a refund of the principal, and in many states the interest as well, minus any fee stated in the contract. Irrevocable plans cannot be refunded to you, though they can generally be transferred to another provider. Insurance-funded plans return the policy's cash surrender value, which may be less than the premiums paid.
Does a prepaid funeral plan count as an asset for Medicaid?
An irrevocable prepaid funeral contract is generally excluded from countable assets for Medicaid eligibility, subject to state limits on the amount. A revocable plan usually is counted, because you could cash it in. Confirm the rules for your state with an elder-law attorney before relying on this.
Can I prepay for cremation?
Yes. Prepaid cremation plans work the same way as prepaid funeral plans and are typically funded through the same trust or insurance arrangements. Direct cremation is one of the least expensive services to prepay, and because it involves fewer third-party charges, more of the cost can usually be guaranteed.
The cost figures in this article come from the National Funeral Directors Association's published statistics, and the consumer protections described come from the Federal Trade Commission's Funeral Rule guidance. State trusting requirements and Medicaid rules differ, so verify the details for your state before signing a contract.
Titan Casket sells caskets and urns directly to families at a fraction of funeral home prices, and through Titan Concierge offers free funeral planning guidance whether you are planning years ahead or arranging a service this week.