

An end of life checklist is a single, organised list of the documents, decisions and practical details your family will need if you become seriously ill or die. A complete end of life planning checklist covers five areas: legal documents (a will or living trust, an advance directive, powers of attorney), medical care decisions, your finances and beneficiaries, your funeral or cremation wishes, and the everyday details such as passwords, bills and contacts that keep a household running. This guide walks through each area in order, so you can work down the list at your own pace and leave your loved ones a plan rather than a puzzle.
Plan Your Farewell with Grace – Our Pre-Planned Caskets Offer Peace of Mind
End Of Life Checklist At A Glance
Use this summary as your working checklist. Each item is explained in the sections that follow.
- Legal documents: last will and testament, revocable living trust (if you need one), living will or advance directive, durable financial power of attorney, health care proxy, organ and tissue donation record.
- Medical decisions: your wishes on life support, resuscitation, palliative and hospice care, and where you want to be cared for.
- Finances and estate: a list of assets and debts, up-to-date beneficiaries on insurance and retirement accounts, executor named, gifts decided.
- Funeral plan: burial or cremation, type of service, casket or urn, final resting place, who to notify, and how it will be paid for.
- Practical directions: where the documents are kept, passwords and device access, contact list, bills and service providers, obituary draft.
1. End Of Life Documents Checklist
These are the papers that give your wishes legal weight. Requirements vary by state, so an estate attorney or your state bar association's referral service can confirm what is valid where you live. The National Institute on Aging publishes a plain-English overview of advance directives and advance care planning that is a good starting point.
Last will and testament. Your will names an executor to settle your estate, says who inherits your property, and is the only document that can name a guardian for minor children. Many people also record their funeral preferences in the will, but keep a separate copy of those wishes somewhere your family can reach immediately: wills are often not read until after the funeral. If you die without one, state intestacy rules decide who inherits, as explained in our guide to what happens if you die without a will.
Revocable living trust. A living trust holds assets such as a home or investments and passes them to your beneficiaries without going through probate court, which keeps the details private and usually faster. It is more work to set up than a will and does not replace one; most people who use a trust also keep a short "pour-over" will. Our comparison of a living trust vs a will explains when each makes sense.
Living will or advance directive. This is a different document from a living trust. A living will tells your doctors and family which medical treatments you do and do not want if you cannot speak for yourself, for example whether you want CPR, a ventilator, tube feeding or comfort-focused care only. Each state has its own form, and many hospitals and state health departments provide them free.
Durable financial power of attorney. This lets a person you trust manage your money, pay your bills and deal with banks or insurers if you become incapacitated. "Durable" means it stays in force after you lose capacity, which is the whole point; a general power of attorney ends the moment you can no longer make decisions. It ends at death, at which point the executor of your will takes over.
Health care proxy. Sometimes called a medical power of attorney, a health care proxy names the person who will make medical decisions for you when you cannot. Choose someone who will follow your wishes rather than their own, tell them what those wishes are, and give them a copy of your living will.
Organ and tissue donation. Register your decision with your state donor registry or on your driver's licence, and tell your proxy. If you want whole-body donation to a medical school, contact the programme in advance; most require pre-registration.
2. Financial And Estate Checklist
Your executor's first job will be working out what you owned and what you owed. Doing that inventory now saves them weeks. List each item with the institution, account number location and rough value: property and mortgages, bank and brokerage accounts, retirement accounts (401(k), IRA, pension), life insurance, Social Security, vehicles and loans, credit cards, business interests, and valuables such as jewellery or collections. Our guide to what happens to debt when you die covers which debts your estate must pay and which die with you.
Check your beneficiaries. Life insurance, retirement accounts and payable-on-death bank accounts pass directly to the beneficiary named on the account, outside your will and outside probate. An out-of-date beneficiary, such as a former spouse, overrides whatever your will says, so review them after any marriage, divorce, birth or death in the family.
Decide on gifts now. Sentimental items can be given while you are alive, which avoids disputes later and lets you see them enjoyed. Larger gifts can have tax consequences, so check with a tax adviser before transferring property or significant sums.
3. End Of Life Care Decisions
Your documents say what treatment you want; this part of the checklist covers where and how you want to be cared for. Talk with your family about whether you want to stay at home with in-home help (and what changes such as ramps, a stairlift or a walk-in shower that would need), or move to assisted living or a nursing facility, and how that would be paid for. If you have a serious illness, learn the difference between palliative care and hospice: palliative care can run alongside treatment at any stage, while hospice care focuses on comfort when treatment has stopped and is covered by Medicare for eligible patients. Record your preferences in your living will and make sure your health care proxy knows them.
4. Funeral Planning Checklist
Deciding your own funeral arrangements is the part of end of life planning that spares your family the most, because these decisions otherwise have to be made within a day or two of a death, under pressure and often at inflated prices. Your funeral plan can be a single page. Cover:
- Burial or cremation, and whether you want a viewing, a religious service, a memorial or a simple graveside gathering.
- Your final resting place: a cemetery plot you already own, a family plot, a columbarium niche, scattering or keeping ashes at home.
- Casket or urn preferences, and any wishes for a green burial or a home funeral, both of which need to be arranged with family in advance because they must happen quickly after death.
- Readings, music, flowers, pallbearers and anyone you particularly want told or invited.
- Veteran status and discharge papers if you are entitled to military funeral honours and burial benefits.
- How it will be paid for: life insurance, a dedicated savings account, or a prepaid funeral plan.
You are not required to buy a casket, urn or any package from the funeral home you use. Under the Federal Trade Commission's Funeral Rule, funeral homes must give you itemised prices and must accept a casket you bought elsewhere without charging a handling fee. Writing that into your plan protects your family from being upsold. Titan Concierge offers free funeral planning help for people planning ahead as well as families facing an immediate need, including price comparisons between local funeral homes, so if you would rather talk your wishes through with someone than fill in a form alone, that is a good place to start.
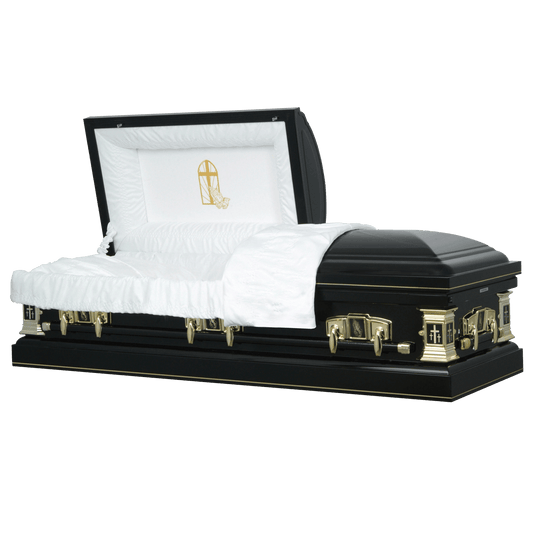
Black and Gold Cross (Made in USA)
Sale price
$2,499
Flat-Top Cloth (Made in USA)
Sale price
$1,199
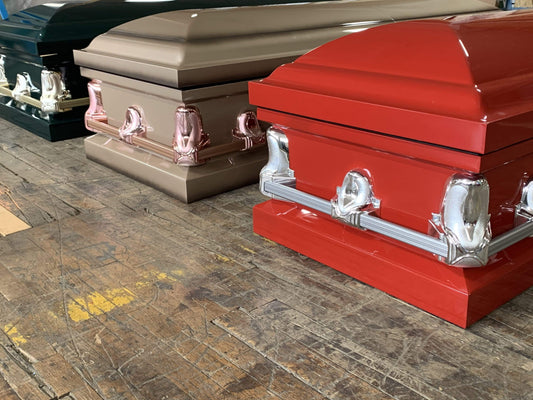
Rustic (Solid Oak) (Made in USA)
$2,499.00 USD
Sale price
$2,999
5. Practical Directions: Passwords, Contacts, Records And Bills
This is the section most end of life checklists leave out and the one families say they needed most. Write a short "how, what, where" document and keep it with your other papers.
Passwords and devices. List the unlock codes for your phone, computer and tablet, and the logins for email, banking, social media and any subscription services, or store them in a password manager and leave the master password with your executor. Without phone access, your family may be unable to reach your contacts, receive verification codes or close accounts. Our guide to handling your digital legacy covers what happens to online accounts after death.
Contact list. Family and friends to notify, your doctors, your attorney, accountant and financial adviser, your employer or pension provider, your faith community, and a neighbour with a spare key. Note who should be called first.
Financial records. Where your insurance policies, account statements, deeds, vehicle titles, tax returns, birth certificate, Social Security card and Medicare details are kept, and the location and key for any safe deposit box.
Location of your will and directives. Say exactly where the signed originals are and who holds copies. An executor who cannot find the will may have to petition the court as though there were none.
Bills and service providers. Mortgage or rent, utilities, insurance premiums, subscriptions and any regular services, with due dates and whether each is on autopay. This keeps accounts from lapsing while the estate is settled.
6. Write Your Obituary And Any Personal Messages
Drafting your own obituary is optional, but it takes a difficult task off your family in the first days after a death and lets you decide how you are remembered. Use our obituary template to get the facts down; your family can add the service details later. Some people also leave letters for specific relatives, or a note explaining the reasoning behind decisions in the will, which can prevent hurt feelings and disputes.
Where To Keep Your End Of Life Checklist
Keep the signed originals of your will, trust, directives and powers of attorney together in one place your executor and proxy can reach without a court order, which usually rules out a safe deposit box in your sole name. Give copies of your living will and health care proxy to your doctor and the person you named. Tell at least two people where everything is. Then set a reminder to review the whole checklist once a year and after any major life event such as a marriage, divorce, birth, death, house move or diagnosis.
End Of Life Checklist FAQ
When should you start an end of life checklist? Now, regardless of age or health. Every adult should have at least a will, a health care proxy and a durable power of attorney, because incapacity can happen at any age. The rest of the checklist can be filled in gradually.
What are the most important end of life documents? If you do nothing else, complete a will, a living will (advance directive), a health care proxy and a durable financial power of attorney. Together they cover who inherits, what medical care you want, and who can act for you if you cannot.
Is a will enough on its own? No. A will only takes effect after death and only covers property that passes through probate. It does nothing if you are alive but incapacitated, and it does not override beneficiary designations on insurance or retirement accounts.
Do I need a lawyer? Simple wills and state advance directive forms can be completed without one. A lawyer is worth the cost if you have a blended family, a business, property in more than one state, a dependant with special needs, or an estate large enough to face estate tax.
Who can help me plan my funeral in advance? A funeral home will sell you a pre-need contract, but you can also plan independently and keep your money. Independent funeral concierge services can record your wishes, compare local providers and help your family carry the plan out when the time comes.
Completing an end of life checklist is not a morbid exercise; it is one of the most practical gifts you can leave the people you love. If any part of it feels overwhelming, Titan Concierge's funeral planning team is available by phone to talk it through at no cost, and Titan Casket is here to help you get the funeral you want at a fair price.